VWAP Bars
v.1.0.0.0 Bar type
Overview
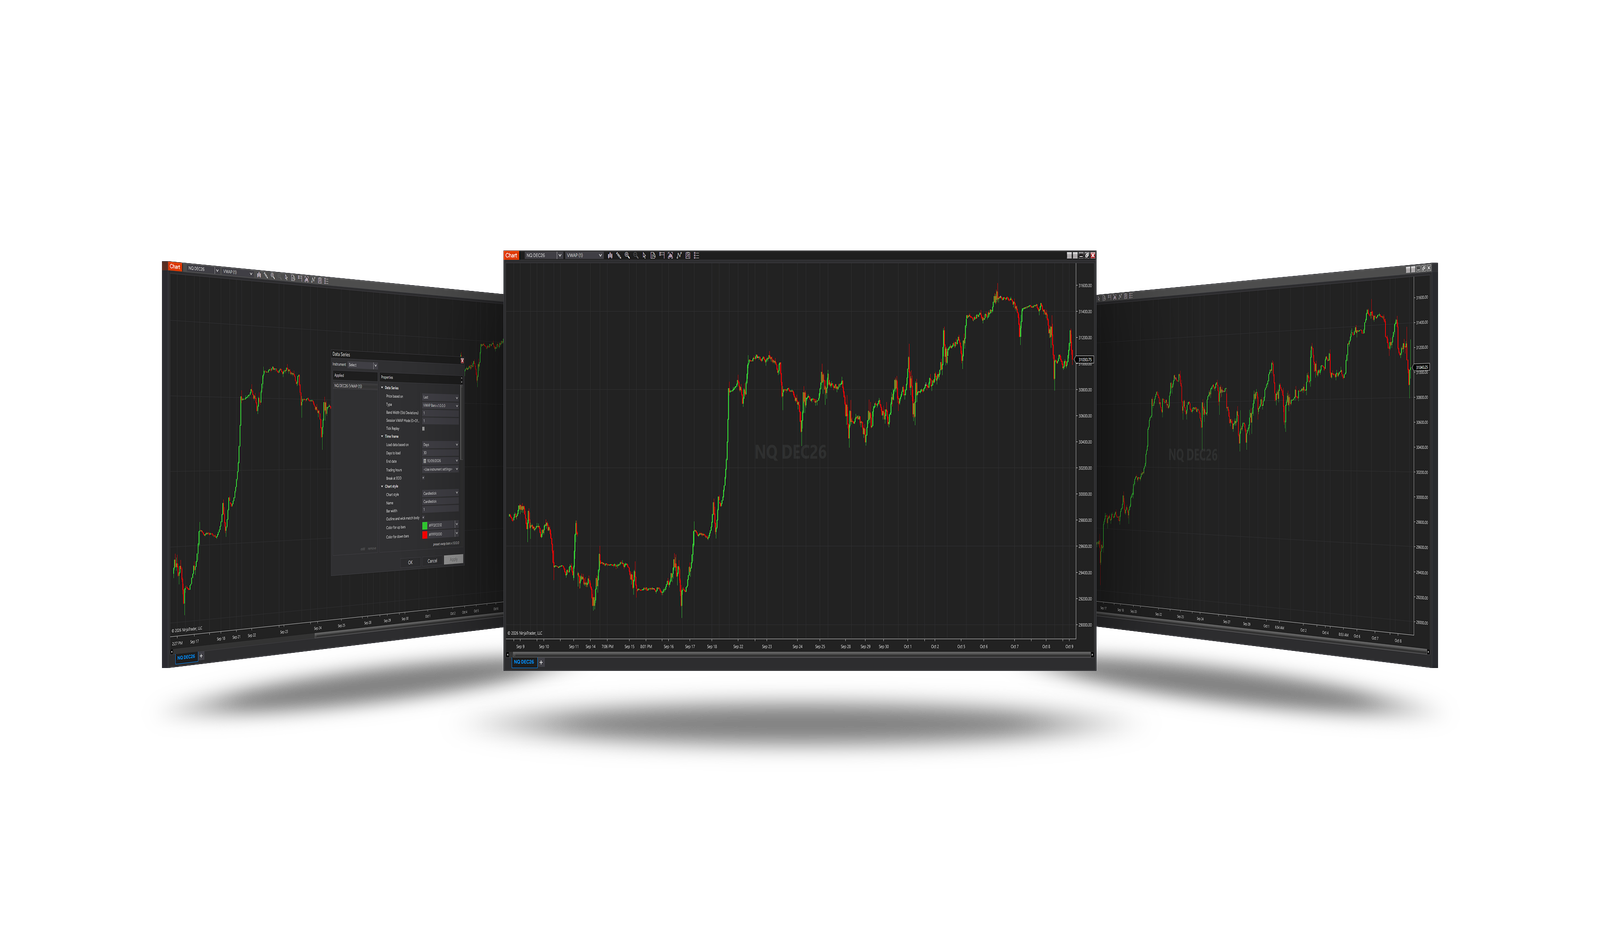
A bar type built on the volume-weighted average price. A new bar starts when the price has moved a set number of standard deviations away from where the current bar began - so bars form on statistically significant moves rather than on time. In a quiet market a bar can last for hours; in a fast one several bars form in minutes.
Settings
In the chart's Data Series window, choose the bar type VWAP:
| Setting | Default | What it does |
|---|---|---|
| Value | 1 | The distance, in standard deviations, the price must move from the bar's start for a new bar. |
| Session VWAP Mode (0=Off, 1=On) | 1 | 1: the deviation is measured with the session's VWAP statistics - steady bars through the session. 0: with each bar's own statistics. |
Good to know
- Bars are decided once per minute, on the minute's close and volume, so a reloaded chart shows exactly the bars real time drew.
- Tick Replay is not used with this bar type.