Parsing Volume
v.3.1.0.0 Built on Strategy Core
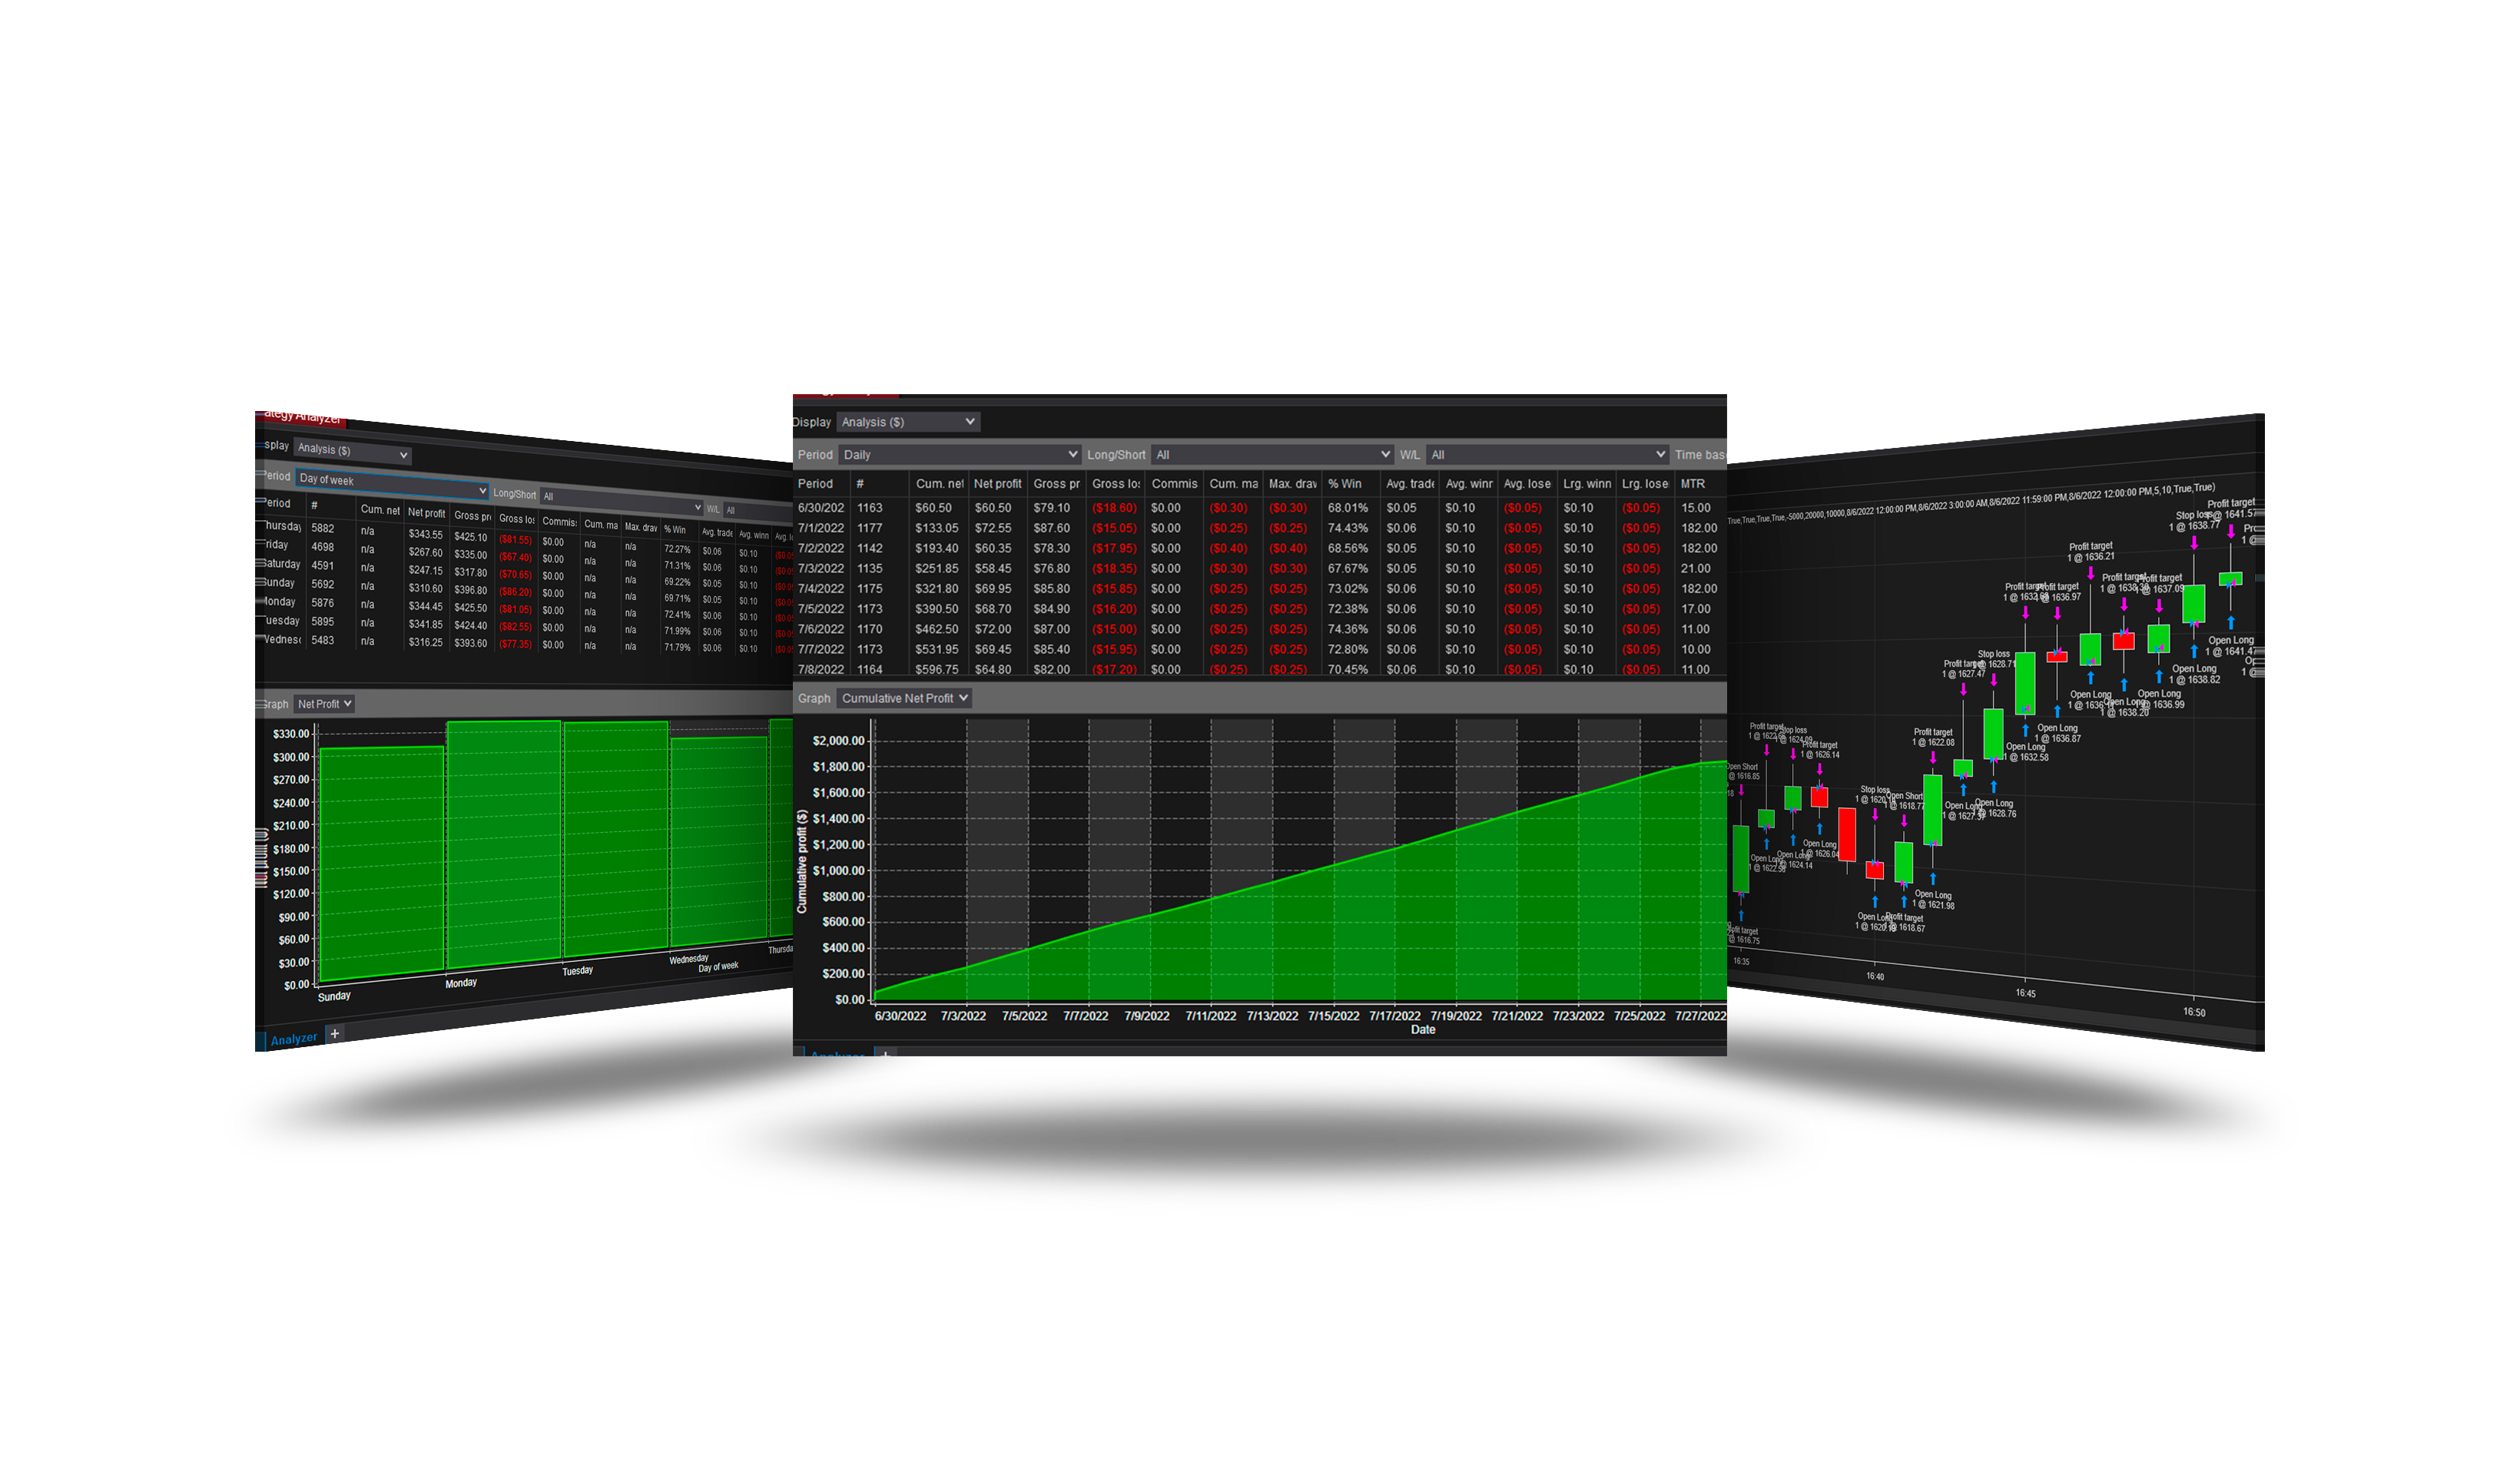
Overview
Scalps large orders resting at the best bid or ask: when a big offer (or bid) stands in the direction of the trend, a stop order just beyond it enters if that volume is eaten through.
How it trades
- Long: at least Large volume contracts on the best ask and the price above the EMA - a buy stop just above the ask.
- Short: the mirror on the best bid, below the EMA.
- Judged on every tick - the large order is the signal, and it is gone by the bar's close.
Test it in Playback, not in the Strategy Analyzer
The signal is the size of the order resting at the best bid or ask. That size is in the Market Replay data, so test the strategy in Playback (Market Replay data downloaded for the days you test). A Strategy Analyzer backtest does not see these sizes and makes no trades. Keep Tick Replay off - NinjaTrader does not run this strategy with it on.
Parameters
| Parameter | Default | What it does |
|---|---|---|
| Large volume | 50 | The size, in contracts, a resting order at the best ask (a long) or bid (a short) must have to be the signal. |
| EMA period | 200 | The trend: longs only above this EMA, shorts only below it. |
Core settings
Order handling, position size, stops and targets, trade management, trading hours, account limits and the ML Engine are core settings - the same in every strategy. Hover a group or a core term for a short explanation.
Strategy Core General & Orders Quantity & Scaling Stop loss & Profit target Trade management Sessions & time Money & News ML Engine Log & Report
Core defaults
This strategy starts with these core settings; change any of them in its settings.
| Group | Setting | Default |
|---|---|---|
| NinjaTrader | Calculate | On each tick |
| Orders | Entry type | Stop market |
| Orders | Entry price | Strategy |
| Orders | Entry offset (ticks) | 5 |
| Quantity | Quantity | 1 |
| Stop loss | Mode | Ticks |
| Stop loss | Ticks | 25 |
| Profit target | Mode | Ticks |
| Profit target | Ticks | 15 |
| Money management (off) | Daily loss | 1000 |
| Money management (off) | Daily profit | 1000 |
Requirements
- Live data, or Playback with Market Replay data downloaded for testing; Tick Replay off.
Version history
v.3.1.0.0 - October 2026
- Changed: the signal follows NinjaTrader's Calculate setting - On each tick by default, so it is taken inside the bar, the moment it appears.
Earlier versions
v.3.0.0.0 - October 2026
- Rebuilt on the Strategy Core: orders, sizing, stops and targets, trade management, sessions, limits and the ML Engine are core settings.
v.2.1.0.0 - May 25, 2026
- Direction forecast: added COT (Commitment of Traders) features.
- Added contract quantity forecast module.
v.2.0.0.0 - Mar 9, 2026
- ML Engine filter feature added.
v.1.1.0.1 - Oct 26, 2025
- Trading hours and days logic updated — if all sessions are disabled, the strategy now runs without time restrictions instead of stopping trading.
v.1.1.0.0 - May 26, 2025
- Added EMA Period Property to set the period of the EMA indicator.
- Added session end position closing function.
- Added descriptive names to exit orders for better understanding of position closure conditions.
- Sorted properties.
- Improved position recovery function.
v.1.0.1.1 - Mar 14, 2024
- Improved conditions for closing a position when the daily loss or profit is reached.
- Changed parameter determining the priority of strategy position or account position.
- Fixed the problem of strategy transition to the next state while placing an entry order.
v.1.0.1.0 - Dec 24, 2023
- Improved conditions for partial fulfillment of orders.
- Improved the function of raising the position after connection loss.
v.1.0.0.9 - Dec 1, 2023
- Improved conditions for partial fulfillment of orders.
- Improved the function of raising the position after connection loss.
- Added functions for order execution log.
v.1.0.0.8 - Nov 12, 2023
- Improved trading session time.
- Improved the function of raising the position after connection loss.
v.1.0.0.7 - Sep 30, 2023
- Improved the function of raising the position after connection loss.
v.1.0.0.6 - Sep 4, 2023
- Added functions to raise position after connection loss.
- Added additional setting for specifying the trading session.
- Updated the manual for the bot.
- Daily profit and drawdown functions can be used in backtest.